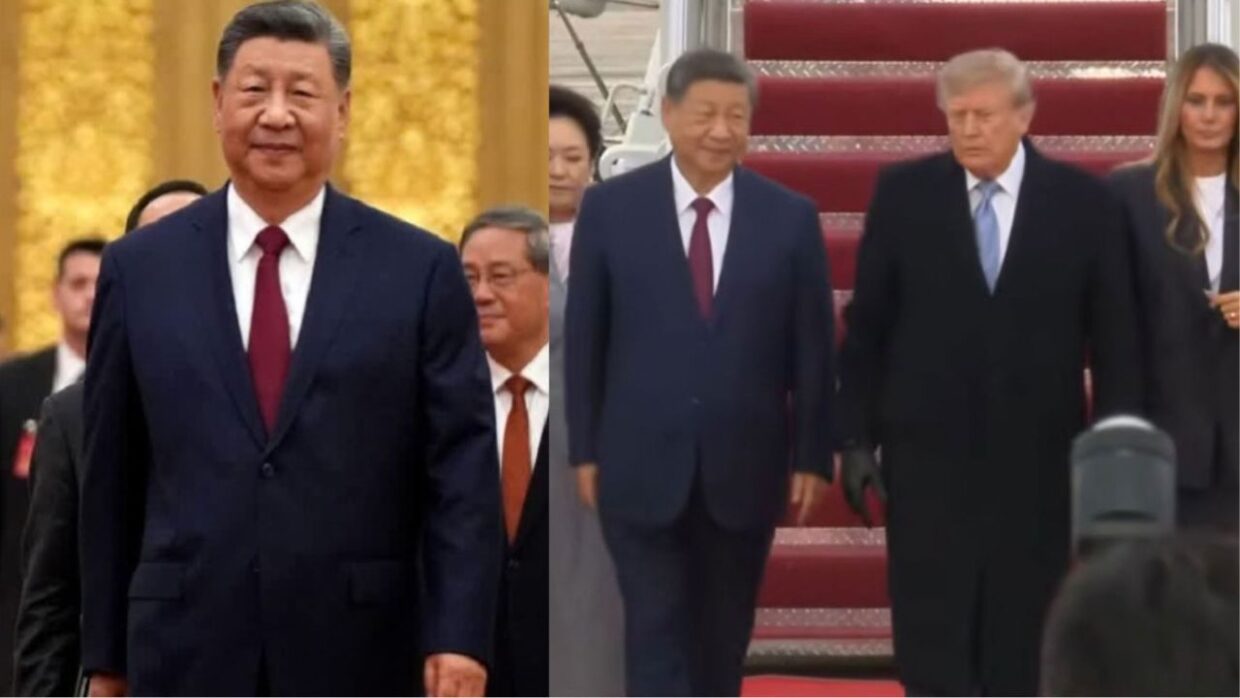
The Iran economy is facing increasing pressure as the war with the United States enters its sixth month and Washington expands financial sanctions. Iranian President Masoud Pezeshkian said the country’s foreign trade has fallen by nearly 35% because of US sanctions and a naval blockade of Iranian ports.
The economic crisis has also attracted the attention of Iran’s highest authorities. The Supreme Leader, Ayatollah Mojtaba Khamenei, has encouraged the administration to address rising costs, unemployment, and other issues affecting people’s daily life.
In a written statement, Khamenei urged firmer action on inflation and the regulation of prices and markets for goods and services. He hasn’t appeared in public since his father, former Supreme Leader Ali Khamenei, was assassinated in an attack on February 28. He was also hurt in the incident.
Iran Economy Faces Rising Inflation and Trade Losses
Iran’s economic problems have worsened as the US intensifies its pressure campaign. Last month, annual inflation hit 66%, exacerbating the hardships faced by consumers and companies.
According to Pezeshkian, Iranian imports and exports have plummeted by almost 35%. He attributed the fall to US sanctions and the naval blockade of Iranian ports.
However, Iran was able to sell approximately 90 million barrels of oil during a brief period in June when the United States permitted Iranian oil sales under a memorandum of understanding. The accord later failed, and talks between Washington and Tehran have since halted.
The Trump administration has referred to its latest pressure campaign as a “economic D-Day.” Washington has warned other countries that companies that continue to conduct business with Iran may face secondary penalties.
So far, the US Treasury has refrained from slapping sanctions on major Iranian commercial partners, including China and India. Such move might have an impact on both the US and the global economies.
New US Sanctions Target Banks and Iran-Linked Entities
The Treasury Department has taken action against a number of other organizations. It imposed sanctions on Egypt’s Banque Misr for commercial relations with Tehran and recommended limits that would prohibit the bank’s branches in the UAE from doing dollar transactions.
Egypt’s central bank and foreign ministry both confirmed that they were in contact with US authorities. It stated that the proposed regulation would only apply to US currency transactions between Banque Misr UAE and correspondent banks.
US officials also announced penalties against a Hong Kong-based entity and a person associated with Iran’s Bank Melli.
Strait of Hormuz Remains a Key Issue
Meanwhile, diplomatic efforts to end the dispute continue. Qatar’s Prime Minister, Sheik Mohammed bin Abdulrahman Al Thani, paid a visit to Tehran on Thursday and emphasized the importance of restoring unrestricted shipping via the Strait of Hormuz.
Iranian Foreign Minister Abbas Araqchi later described the negotiations as “creative.” Qatar and Pakistan earlier assisted in negotiating the June agreement, which resulted in a brief cease-fire.
Control of the Strait of Hormuz is still a major source of controversy. According to US military commanders, American personnel have eliminated sea mines laid by Iran’s Islamic Revolutionary Guard Corps in the waterway.
President Donald Trump has stated on numerous occasions that the strait is open. The IRGC navy denies this assertion, claiming that ships must still obtain Iranian clearance to sail through.
According to shipping numbers issued on Friday, only seven cargo vessels passed the strait on Thursday, compared to 17 the day before and a 10-day average of 15.
- Join our whatsapp channel for daily updates.
- Follow tazatimesnews Telegram Channel for latest news alerts.
- Follow TazaTimesNews on TruthSocial for exclusive updates
- Also reads : Yogi Government Announces Free Bus Travel for Women on Raksha Bandhan